Kiddipedia Financial Support Information
When the cost of running a family keeps rising, getting back on track takes more than cutting back. Here’s how to understand the pressure on your household finances, make better decisions under stress and create a recovery plan that works in real life.
There’s a particular kind of stress that comes from knowing your money should cover the bills, but somehow the numbers no longer add up.
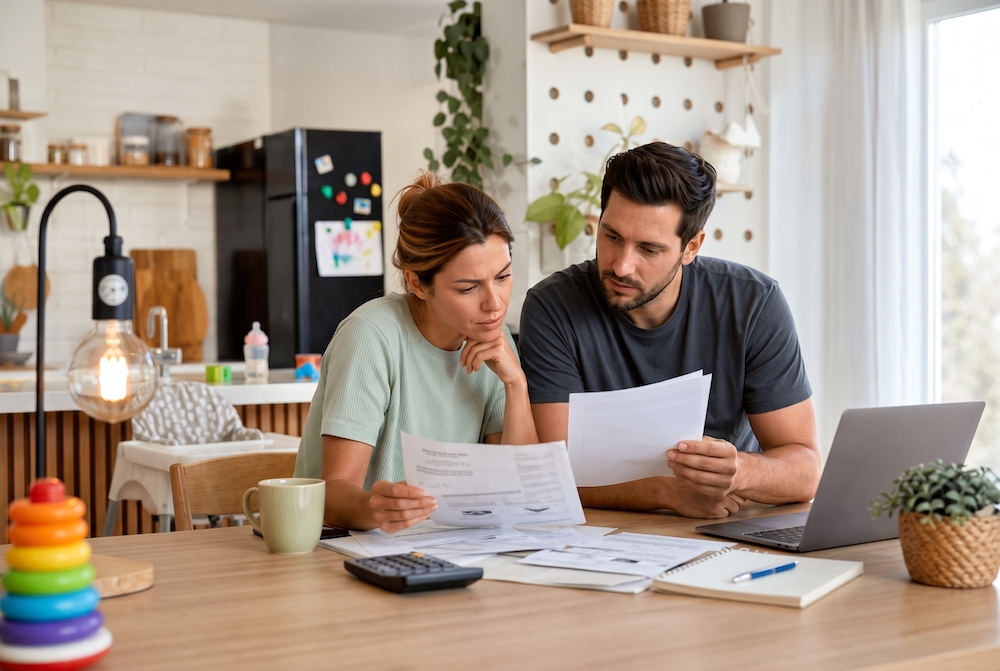
Perhaps both parents are working, yet childcare, groceries, fuel and the mortgage seem to swallow every pay packet. Maybe your child needs new school shoes the same week the car needs repairs. Or perhaps you have been managing reasonably well until an illness, reduced income or unexpected expense turns an already tight month into a difficult one.
When this happens, it is easy to assume you need to become more disciplined with money. But family finances are rarely that simple. Income can be irregular, essential expenses arrive at inconvenient times, and the costs of raising children change as they grow. Even a household that plans carefully can be caught out when several expenses land together.
Australian data puts this pressure into perspective. The Australian Bureau of Statistics (ABS) reported that 25.3% of households experienced at least one cash-flow problem during 2025. Meanwhile, 21.7% of households said they could not raise $2,000 within a week for something important. For one-parent families with dependent children, the latter figure was 42%, compared with 23% of couple families with dependent children. These figures show how quickly financial resilience can become an issue, particularly when a household has fewer resources to fall back on. (ABS, General Social Survey: Summary Results, Australia, 2025).
The answer is not always to spend less. Sometimes it is to change the timing of payments, address an expensive debt, check whether you are receiving the support available to your family, or speak to a lender before a temporary setback becomes a longer-term problem.
Let’s look at what can make household finances difficult to manage — and what parents can do about it.
Common Financial Hurdles in Family Households
1. The problem is not always how much you earn — it is when the money arrives
A household can look financially stable on paper and still struggle to pay its bills on time.
Imagine that your salary arrives fortnightly, but your mortgage or rent, childcare fees, car insurance and utility direct debits fall due during the same week. The money coming in over the month might technically cover the expenses, but the account balance can become uncomfortably low before the next payday.
This is a cash-flow problem, rather than necessarily a spending problem.
The distinction matters because repeatedly using a credit card or buy now, pay later service to bridge the gap can make the next pay cycle even tighter. You are effectively using tomorrow’s income to cover yesterday’s expenses, leaving less available for the bills that are still to come.
What makes the difference? Look at the dates money enters and leaves your account, not just the monthly totals. A simple calendar showing paydays, direct debits, school expenses and loan repayments can reveal whether the problem is a genuine shortfall or a mismatch in timing.
If a bill date is creating unnecessary pressure, ask the provider whether it can be moved to better align with your income. Not every organisation will agree, but it is worth asking before relying on credit to get through the week.
2. Family expenses are predictable in principle, but difficult to predict precisely
School uniforms, registration renewals, dental appointments, birthday parties and holiday care are not unusual surprises. Most families will face them at some point. The difficulty is knowing exactly when they will arrive and how much they will cost.
A family might manage its weekly groceries and mortgage repayments comfortably, only to face school contributions, a car service and an annual insurance premium within a fortnight. None of those costs is especially unusual on its own. Together, they can derail the budget.
This is sometimes called expense bunching: several costs land close together, creating pressure that a monthly average does not reveal.
A practical response is to separate everyday spending from expenses that occur periodically. Review the previous 12 months of bank transactions and identify annual or irregular costs, including school expenses, car registration, insurance, medical appointments and Christmas.
If you expect to spend $1,200 on an annual expense, for example, setting aside $100 a month may make the payment easier to manage. If there is no spare $100, that is useful information too. It tells you the plan needs to be adjusted, the expense needs to be reduced where possible, or additional support may be needed.
The aim is not to build a perfect budget. It is to reduce the number of expenses that arrive feeling like a financial emergency.
3. The cost of raising children changes faster than a family budget
Financial plans can become outdated without parents doing anything wrong.
Childcare arrangements change. Children grow out of clothes and shoes. School-age children may need devices, excursions, uniforms or extra learning support. Older children can bring higher transport, sporting and social costs. Meanwhile, a parent may reduce working hours to care for a child or manage a family health issue.
These changes can affect both sides of the household budget: what the family spends and what it earns.
For example, a parent returning to work might expect an increase in household income, only to find that childcare fees, commuting and additional care arrangements absorb much of the extra money. The return to work may still be worthwhile, but the real financial benefit can look different from the salary figure alone.
When family circumstances change, review the whole arrangement rather than focusing on one number. Consider take-home pay, childcare costs, transport, changes to government payments and any additional expenses associated with working.
Families may also wish to check their eligibility for the Australian Government’s Child Care Subsidy and Family Tax Benefit. Eligibility and payment amounts depend on individual circumstances, so use the official information rather than assuming you do or do not qualify.
4. Financial stress can make the next decision harder
Money worries do not stay neatly contained in a bank account. They can affect sleep, concentration, relationships and the energy available for everyday parenting.
When several bills are overdue, it can be difficult to decide which one to deal with first. Some parents avoid opening emails or answering calls because they feel overwhelmed. Others make quick decisions simply to stop the immediate pressure, even if the decision costs more over time.
This is not a character flaw. It is one reason a financial plan needs to be manageable when someone is already under stress.
The Australian Securities and Investments Commission (ASIC) has highlighted problems in the way some home-loan hardship processes have worked. In its review of major lenders, ASIC found that 35% of customers dropped out of the hardship assessment process at least once, and 40% of customers who received assistance fell into arrears immediately after that assistance period ended. (ASIC, Hardship, not as hard to get help).
The lesson for families is important: temporary relief is not always the same as a sustainable recovery plan. A lower repayment may help this month, but if the repayment returns to an unaffordable level later, the underlying problem remains.
When you are under pressure, focus on the next decision that will make a meaningful difference. That might be contacting a lender, checking an entitlement, asking a provider for a payment arrangement or getting independent financial counselling. You do not have to solve every part of your finances in one sitting.
As seen above, there are multiple avenues where income loss can potentially happen in a household. This is why it’s essential to manage your family finances wisely to ensure a happy and stable childhood for your entire family for years to come.
How to Overcome Financial Setbacks as a Family
1. Assess Your Family’s Current Financial Situation
Before making cuts or taking on another financial product, work out what is actually happening.
A bank balance tells you how much money is available today. It does not necessarily tell you whether you can cover the next fortnight’s bills, whether a debt is becoming more expensive, or whether your current income can sustainably meet your family’s needs.
Start by looking at three things:
- Your essential commitments: housing, utilities, basic food, necessary transport, childcare, medical costs and minimum debt repayments.
- Your income and timing: take-home pay, government payments, irregular earnings and the dates these arrive.
- Your financial pressure points: overdue bills, debts attracting high interest or fees, upcoming annual expenses and costs that have increased recently.
If your income varies, avoid building the plan around your best month. Use a realistic estimate of the income you can rely on, then decide how to handle additional earnings when they arrive.
For example, a self-employed parent may have a strong month followed by several weeks of quiet trading. Treating the strongest month as the normal income can make the household appear more financially secure than it is. A more useful approach is to identify the minimum reliable amount available for household commitments and plan variable spending around that.
The Australian Government’s Moneysmart budgeting guidance can help you map income and expenses. But the most useful budget is one that reflects your actual bank transactions, not an idealised version of how you think your family should spend.
Look for the gap, not someone to blame. If essential expenses are already greater than reliable income, cancelling a streaming subscription will not solve the underlying problem. It may still be worth reviewing smaller costs, but the larger task is to address the structural shortfall — through available assistance, a change to major expenses, additional reliable income where possible, or early conversations with creditors.
For families experiencing financial difficulty, free financial counselling through the National Debt Helpline can help assess the situation and explore options. You do not need to wait until every bill is overdue.
If you lack the funds but have a bad credit score to apply for a traditional loan, you can always consider getting flexible loan options for bad credit in a pinch.
2. Learn What Costs You Can Cut — Without Cutting the Things Your Family Needs
When money gets tight, “cut back” is often the first advice parents hear. The problem is that families can only cut so far, especially when most of their spending goes towards housing, food, transport and care.
A more useful approach is to distinguish between expenses you can change quickly, expenses you can renegotiate, and expenses that are essential to your family’s wellbeing or ability to earn an income.
For example, cancelling a subscription you rarely use may free up a small amount immediately. Reviewing an insurance renewal or changing an expensive phone plan could produce a more meaningful ongoing saving. But reducing childcare without considering the effect on work, or delaying necessary healthcare, may create larger problems elsewhere.
Try reviewing expenses in this order:
First, investigate large recurring commitments. Check whether your current internet, mobile, insurance and energy arrangements still offer value. Compare the full cost, including introductory periods, excesses, coverage and exit fees. A cheaper policy or plan is not necessarily better if it leaves your family exposed to a significant cost later.
Next, look at costs that have crept up. Grocery shopping, takeaway meals, convenience purchases and children’s activities can change as family routines change. Rather than assuming every purchase is wasteful, look for patterns. Are you buying extra groceries because meal planning no longer fits your work schedule? Are late finishes leading to takeaway several nights a week? The solution may be to make the routine easier, rather than relying on willpower at the end of a long day.
Then, protect the spending that prevents bigger problems. Necessary car maintenance, prescribed treatment, adequate insurance and costs that allow a parent to keep working may be important even when money is tight. Delaying them can shift the expense into a more expensive emergency later.
Consider a family that spends extra on convenience food because both parents finish work late and still have school pick-up, homework and bedtime to manage. Simply telling them to stop buying takeaway may not be realistic. Preparing two simple meals ahead of time, keeping easy pantry options available or changing one particularly difficult evening could reduce the cost without adding an unreasonable amount of work.
This is the kind of change that lasts: make the lower-cost choice easier to repeat.
It is also worth checking whether your family is receiving the support it is eligible for. Services Australia’s Payment Finder can help estimate potential payments, including Family Tax Benefit and child care assistance. An estimate is not a guarantee of eligibility, but it can help you decide whether to investigate further.
3. Clear Outstanding Debt — By Understanding Which Debt Is Causing the Most Damage
Debt can make a tight household budget even more difficult because repayments reduce the money available for current expenses. Interest and fees can also mean that a balance takes longer to clear than expected.
But not all debt works in the same way, and a family under financial pressure needs to understand the difference before deciding what to tackle first.
The clear way to push past this is by dealing with your outstanding debt as fast as you can. Make repayments early if you find yourself in a stable financial position, particularly for loans with high interest rates. Begin by listing each debt, its outstanding balance, interest rate, fees, minimum repayment and due date. Include credit cards, personal loans, car finance, buy now, pay later balances and overdue bills. Do not rely only on the minimum repayment shown on a statement; check the terms and the cost of carrying the balance.
Then ask three questions:
- Is any essential account overdue? Housing, utilities and other commitments that affect your family’s stability may need urgent attention.
- Which debts are growing fastest? High-interest balances and fees can consume money that could otherwise go towards reducing the debt.
- Are the required repayments affordable at your current income? If not, the priority may be to request hardship assistance rather than trying to make an unsustainable repayment plan work.
If you can meet all essential expenses and minimum repayments, you may be able to direct extra money towards the debt with the highest interest rate. This can reduce the interest paid over time, depending on the terms of your debts and whether additional fees apply.
Some people prefer to clear a smaller balance first because the progress is easier to see. That can be motivating, but it is important to understand the potential trade-off: paying off a small, low-interest balance first may cost more in interest if a larger, higher-interest debt continues to grow.
There is no value in choosing a repayment strategy that looks good on paper but leaves your household unable to cover groceries or an essential bill. If you cannot meet the minimum repayments, contact the lender or credit provider and explain your circumstances. ASIC’s Moneysmart financial hardship guidance explains how to request assistance. Depending on your situation, a provider may consider options such as a payment plan or changes to repayments.
If you are dealing with several creditors, collection activity or debts you cannot realistically repay, a free, independent financial counsellor can help you understand your options and communicate with creditors. Contact the National Debt Helpline on 1800 007 007.
Be cautious about taking out a new loan to cover existing repayments. Consolidation may be suitable in some circumstances, but a lower advertised repayment does not automatically mean the debt will cost less. Compare the interest rate, fees, loan term and total amount repayable, and consider whether the new arrangement could put an asset or essential household budget at risk.
For more information on outstanding debt, see Understanding Outstanding Debt: Definition and Explanation.
4. Contact Providers Before a Difficult Month Becomes a Longer-Term Problem
When a bill cannot be paid on time, avoiding the provider rarely makes the situation easier. Contacting them early gives you the opportunity to explain what has changed and ask what assistance is available.
This is particularly important if your household income has fallen because of illness, reduced work, separation, caring responsibilities or an unexpected expense.
Depending on the type of bill and provider, you may be able to ask about a payment extension, instalments, a hardship arrangement or other support. The options vary, and not every request will be approved, but it is better to understand what is available than to assume there is no flexibility.
When you contact a provider, be specific. Explain what you can afford, when your circumstances may change and whether the difficulty is temporary or ongoing. If an arrangement is offered, ask what happens when it ends. ASIC’s findings on customers falling back into arrears after hardship assistance underline why the next stage matters as much as the immediate relief.
Keep a record of the conversation, the agreed amount and the dates. If the proposed arrangement is still unaffordable, say so rather than agreeing to payments you are unlikely to maintain.
A realistic arrangement is more useful than a promise made under pressure.
5. Build Financial Breathing Room Before Trying to Build a Perfect Emergency Fund
An emergency fund can help protect a family from unexpected costs, but telling a household that is already short of money to save several months of expenses may feel impossible.
Start smaller. If you can set aside a modest amount without missing an essential payment or increasing high-cost debt, it may help cover a future expense without reaching for credit. The amount matters less at first than finding a way to keep some money available for a genuine emergency.
For example, if your car is essential for getting to work and school, an unexpected repair could affect both your income and your family routine. Even a small buffer may give you more options than having no available funds at all.
However, do not divert money into savings while ignoring overdue essentials or unaffordable debt repayments. The order of priorities depends on your circumstances. A family that is struggling to pay for food or housing needs a different plan from a family that can cover its essentials but has little left at the end of the month.
Once your immediate situation is more stable, you can gradually build towards a larger reserve. Moneysmart’s guide to saving for an emergency fund explains how to approach this over time.
The goal is not to compare your savings with another family’s. It is to give your own household a little more room to absorb the next unexpected expense.
Why Getting Back on Track Takes More Than Cutting Back
When household finances become difficult, it is tempting to focus on one big fix: earn more, spend less, clear every debt or save a certain amount. In reality, recovery often comes from dealing with different problems in the right order.
If your income is irregular, focus first on the timing of money coming in and going out. If essential expenses exceed reliable income, investigate the larger costs and support available to your family. If debts are growing or repayments are no longer affordable, speak with creditors and seek independent advice early. If your finances are stable but vulnerable to unexpected costs, work towards a buffer you can realistically maintain.
And remember that a budget is a tool, not a measure of how well you are doing as a parent.
Some families have more flexibility than others. A household with one income, a child with additional needs, high housing costs or limited family support may have fewer options to reduce expenses quickly. Comparing your finances with someone else’s can obscure those differences.
A better question is: What is the next change that would make our household more stable, and what support would help us make it?
That question leaves room for practical action without pretending every financial problem can be solved by cutting back on small purchases.
Australian Resources That Can Help
If your family is navigating financial pressure, these Australian services can help you understand your options:
- Moneysmart: Australian Government guidance on budgeting, debt, saving and financial hardship.
- Services Australia Payment Finder: Estimate potential payments, including family assistance and child care support.
- National Debt Helpline: Free, confidential and independent financial counselling. Call 1800 007 007.
- ASIC Moneysmart — Financial hardship: Understand how to contact a lender or credit provider when repayments become unaffordable.
Seeking help early is not an admission of failure. It is a way to understand your choices before the situation becomes harder to manage.
Where to Go from Here
Financial setbacks can happen even when a family is doing its best. The costs of raising children change, unexpected expenses arrive, and sometimes income simply cannot keep pace with what a household needs.
You do not have to overhaul every part of your financial life at once. Start by identifying the real source of the pressure, then focus on the decision most likely to make a meaningful difference. That may mean changing payment dates, checking family entitlements, negotiating with a provider, reviewing a major expense or asking for help with debt.
Most importantly, do not wait until everything feels unmanageable before reaching out. A clear picture of your finances, a realistic plan and the right support can help your family take the next step towards greater stability.
We hope that this article has helped you navigate financial hurdles more easily. All the best in creating wealth for your family!
References
- Australian Bureau of Statistics. (2026). General Social Survey: Summary Results, Australia, 2025. https://www.abs.gov.au/statistics/people/people-and-communities/general-social-survey-summary-results-australia/latest-release
- Australian Securities and Investments Commission. (2025). Hardship, not as hard to get help (Report 815). https://www.asic.gov.au/regulatory-resources/find-a-document/reports/rep-815-hardship-not-as-hard-to-get-help/
- Australian Securities and Investments Commission. Moneysmart: Financial hardship. https://moneysmart.gov.au/managing-debt/financial-hardship
- Australian Securities and Investments Commission. Moneysmart: Budgeting. https://moneysmart.gov.au/budgeting
- Australian Securities and Investments Commission. Moneysmart: Save for an emergency fund. https://moneysmart.gov.au/saving/save-for-an-emergency-fund
- Services Australia. Child Care Subsidy. https://www.servicesaustralia.gov.au/child-care-subsidy
- Services Australia. Family Tax Benefit. https://www.servicesaustralia.gov.au/family-tax-benefit
- Services Australia. Online estimators. https://www.servicesaustralia.gov.au/online-estimators?context=64107
- National Debt Helpline. What is financial counselling? https://ndh.org.au/financial-counselling/what-is-financial-counselling/
- Tratta. Understanding Outstanding Debt: Definition and Explanation. https://www.tratta.io/blog/understanding-outstanding-debt-definition-explanation
Editorial note: This article provides general information, not individual financial, legal or tax advice. Eligibility for government payments and hardship assistance depends on individual circumstances. Check official information before making financial decisions.